Big private equity deals rarely move in a straight line. When an asset hits the market with a hefty price tag attached, the initial excitement often gives way to a quiet standoff between sellers wanting top dollar and buyers hunting for a discount. That dynamic is playing out right now behind the scenes of the global food industry.
Elliott Investment Management has reportedly entered the picture regarding Flora Food Group. If you've been following corporate restructurings, Paul Singer's activist firm rarely shows up just to browse. They smell an opportunity where a valuation gap has stalled a transaction.
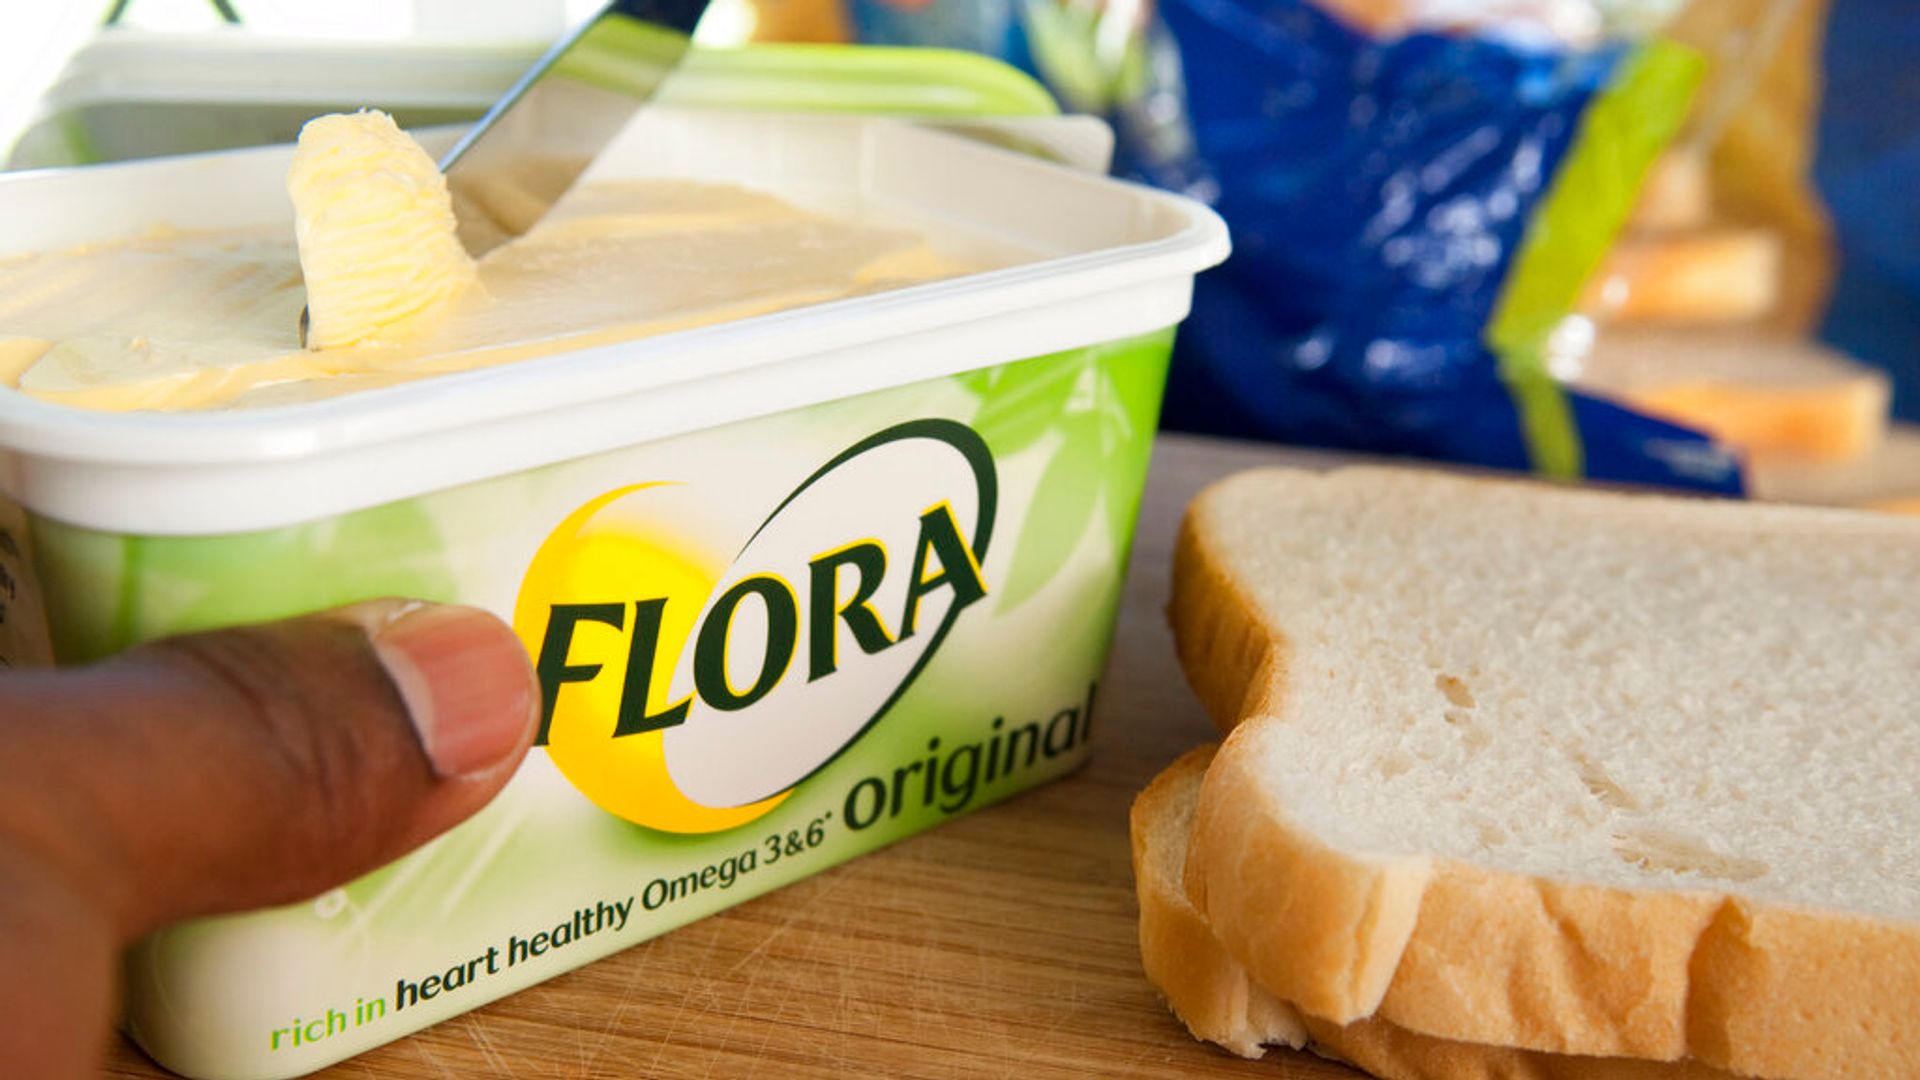
For months, private equity heavyweight KKR has tried to orchestrate a lucrative exit from the massive spreads and margarine producer—formerly known as Upfield when it spun out of Unilever's sprawling consumer goods empire. KKR initially pinned high hopes on valuations reaching up to seven billion euros or even touching ten billion dollars under peak market assumptions. Prospective trade buyers and traditional buyout shops, however, haven't exactly rushed forward to match those ambitions.
Enter Elliott. Known for shaking up boardrooms, accumulating strategic stakes, and forcing complex deals over the finish line, their interest changes the math for everyone involved.
The Valuation Standoff
Let's look at why this deal is dragging. Flora Food Group houses household names like Becel, Bertolli, Blue Band, and Violife. These are stable, cash-generating brands that line supermarket shelves across the globe. Stability alone doesn't always command hyper-growth multiples, though.
Consumer goods markets have shifted underneath legacy food producers. Inflation, shifting dietary habits, and private-label competition mean traditional margin expansion is a grind. When KKR appointed advisers to explore a sale, prospective buyers balked at the initial seven billion euro target.
That friction creates a playground for distressed asset experts and activist investors. Elliott doesn't necessarily need to buy the whole company outright to make money. They can accumulate influence, structure debt packages, or pressure management to streamline operations further. They specialize in unlocking value when a primary auction stalls out.
Trimming the Portfolio to Ease an Exit
Before Elliott started circling, KKR and Flora's leadership team were already busy rearranging the furniture to make the balance sheet more attractive.
Take the Latin American business, for example. Flora offloaded those operations to Alicorp in a deal worth around $151 million. Streamlining regional exposure helps tidy up complex corporate structures, making the core European and North American assets easier for a single buyer to digest.
At the same time, the company walked back some of its aggressive, purely plant-based pledges. While brands like Violife dominate vegan cheese alternatives, the broader market demand for traditional dairy blends forced a pragmatic pivot. Sticking rigidly to a zero-dairy narrative wasn't maximizing profit in a volatile grocery landscape. Management realized they had to follow consumer wallets rather than ideological trends.
What Happens Next in the Process
An auction process doesn't simply die because the original price expectations were too high. It evolves.
Other players like Apollo Global Management have floated around the rumor mill, but large-scale consumer buyouts require immense debt financing packages that banks price carefully in current monetary environments. If traditional private equity syndicates struggle to clear the financing hurdle alone, creative deal structures become mandatory.
This is precisely where Elliott thrives. Whether they end up partnering on a consortium, taking a sizeable financial position in the debt layer, or steering the eventual resolution of the sale, their presence signals that a conclusion is coming. KKR wants a clean break, but they might have to accept a haircut on their original valuation goals to get it done.
Watch how the advisory teams handle the next round of bids. When activist capital joins an stalled mega-sale, the final chapter rarely resembles the original sales pitch.